Treasury & Operations
8 Multicurrency Payment Software Options
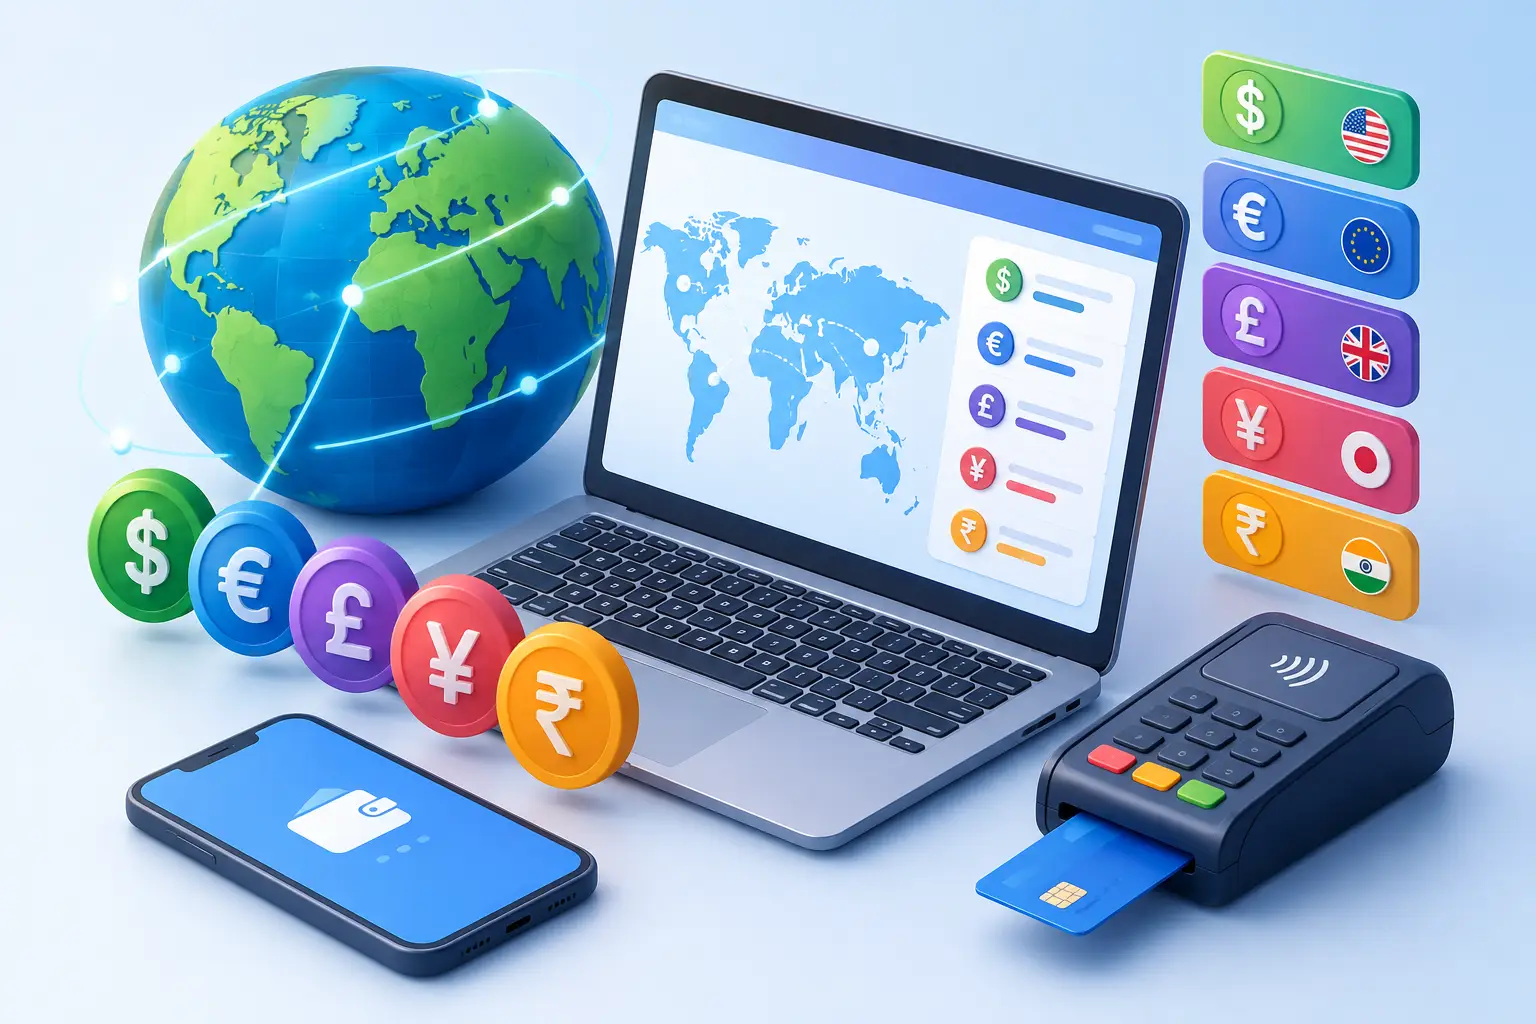
A supplier invoice in euros, contractor payments in dollars, and customer receipts in naira can turn a routine finance day into a chain of costly conversions. The right multicurrency payment software options reduce that friction by bringing balances, FX execution, payment routing, approvals, and compliance into a more controlled operating process.
For African businesses trading internationally, the question is not simply which platform holds the most currencies. It is whether the provider can support the corridors that matter, show the true cost of conversion, settle reliably, and provide the documentation your finance team needs when a transaction is reviewed.
What multicurrency payment software should solve
Multicurrency software gives a business one place to receive, hold, convert, and send funds across more than one currency. At its best, it replaces disconnected bank portals, manual spreadsheets, and ad hoc FX requests with a clearer payment workflow.
The practical value is not limited to convenience. A well-chosen platform can help a business time conversions more deliberately, reduce unnecessary intermediary charges, and separate employee permissions from final payment approval. It can also make reconciliation less painful by attaching payment references, beneficiary records, and transaction data to the same operational process.
That said, no platform eliminates foreign exchange risk or local banking requirements. Exchange rates move, payment cutoffs apply, and some destinations require more beneficiary information than others. The goal is better visibility and execution, not the promise of instant payments in every currency and every market.
8 multicurrency payment software options to consider
The best choice depends on your payment volume, the countries involved, and whether your priority is receiving funds, paying suppliers, managing FX, or building payments into your own product. These eight options describe the main platform models worth evaluating.
1. Multi-currency business account platforms
These platforms allow businesses to maintain balances in several currencies and make payments from the relevant balance. They suit companies that regularly collect funds in major currencies such as USD, GBP, and EUR, then use those funds to pay overseas expenses without converting every transaction immediately.
This model can reduce repeat conversion costs, but finance teams should confirm where accounts are issued, whether they are local account details or collection details, and how safeguarded funds are handled. A balance in a currency is useful only if it can be funded and paid out reliably in the markets you serve.
2. FX-first payment platforms
An FX-first provider is built around buying, selling, and swapping currencies before or alongside payment execution. This is often the stronger option for importers, exporters, agencies, and treasury teams whose margin is sensitive to exchange-rate movements.
Look beyond a headline rate. Ask how the rate is calculated, whether the provider discloses its spread and fees, how long a quoted rate is valid, and when funds must be received before conversion can be completed. For larger or recurring payments, access to an experienced dealing team can be as valuable as the online interface.
3. Global supplier payment platforms
Businesses paying overseas manufacturers, freight partners, software vendors, or professional service providers may need a supplier-focused payment platform. The key advantage is payment routing: a platform may offer local delivery methods in certain markets instead of relying only on international wires.
Local payouts can be faster and easier for beneficiaries, but availability differs by country and currency. Confirm the delivery currency, estimated payment time, cutoff times, required invoice or trade documentation, and whether the recipient pays any incoming bank fees. Those details determine the real supplier experience.
4. Payroll and contractor payment systems
Companies with distributed teams often need to pay people in their preferred local currencies while keeping payroll controls centralized. Contractor and payroll platforms can organize payment batches, pay dates, recipient onboarding, and reporting for a remote workforce.
This option is useful when the workforce payment process is the main problem. It may be less suitable for businesses that also need active FX management, trade settlements, or complex collections. Review whether the service supports the employment and tax model you use rather than assuming a payment tool handles every payroll obligation.
5. Accounts payable automation tools with FX features
Accounts payable tools add workflow discipline to international payments. They commonly focus on invoice capture, approval rules, purchase-order matching, scheduled payments, and accounting-system synchronization. Some also provide currency conversion and cross-border payment capabilities.
For a growing SME, this can be a practical fit when the chief concern is preventing duplicate payments or ensuring no one person can create and release a payment alone. The trade-off is that FX coverage and corridor depth may not match a specialist provider. Review both the workflow features and the underlying payment network.
6. Marketplace and mass-payout platforms
Marketplaces, platforms, and digital businesses often need to pay many sellers, creators, agents, or affiliates at once. Mass-payout software supports bulk uploads or API-driven payment instructions, beneficiary management, status tracking, and payment notifications.
This model is designed for scale, not necessarily for individualized treasury decisions. It is a strong choice when payment volume is high and amounts are relatively standardized. Before selecting one, test its exception handling: failed payments, changed bank details, returned funds, and beneficiary verification are where operational teams spend their time.
7. API-based payment infrastructure
API-based providers allow a business to embed account creation, FX quotes, beneficiary validation, payment initiation, and status updates into its own systems. This is relevant for fintechs, enterprise platforms, and businesses that want a payment flow that matches their existing product or operations.
The benefit is control. The responsibility is greater, too. Your team must assess documentation quality, uptime expectations, webhooks, authentication, reconciliation data, sandbox testing, and the provider's support model when transactions need urgent attention. API access is not automatically better than a dashboard if your volume does not justify the integration work.
8. Integrated FX, payments, and compliance platforms
An integrated provider combines currency conversion, local and cross-border settlement, and compliance support in one operating relationship. This can be particularly valuable for businesses working across Africa-to-global corridors, where payment execution and identity or business verification often need to work together.
The advantage is fewer handoffs between an FX broker, payment processor, and compliance vendor. ParkPay is an example of this approach, combining FX services, B2B payment infrastructure, and API-based verification capabilities for customers managing international financial activity. The right fit still depends on supported corridors, transaction requirements, and the level of operational support your business needs.
How to compare providers beyond the exchange rate
A low advertised FX rate does not necessarily mean a low-cost payment. The effective cost includes the provider's spread, transfer fees, correspondent bank charges where applicable, receiving fees, and the risk of delays that affect supplier relationships or delivery schedules. Request a clear illustration using a realistic transaction size and destination.
Coverage should be equally specific. A provider may support a currency for conversion but not for local payout, or may support payments to a country only with additional documentation. Map your top currencies, origin countries, destination countries, monthly volume, and typical payment sizes before beginning provider discussions.
Security and compliance deserve the same attention as pricing. Check the provider's licensing or regulatory status in the relevant jurisdiction, customer due diligence process, data protection controls, transaction monitoring approach, and procedures for handling payment recalls or fraud reports. Proper checks may add time to onboarding or an occasional transaction review, but they protect the business and help sustain reliable payment access.
For finance teams, controls are decisive. Ask whether the system offers role-based access, maker-checker approvals, beneficiary change controls, downloadable statements, audit trails, accounting exports, and payment-status visibility. A platform that saves a small amount on FX but creates hours of monthly reconciliation work may not be the efficient option.
A practical selection process
Start with actual payment data from the last three to six months. Identify the currencies you received and paid, your largest corridors, recurring beneficiaries, average payment size, and the points where staff had to intervene manually. This produces a more useful requirements list than choosing based on a generic feature comparison.
Next, test the provider against a normal business scenario. Can your team obtain a quote, add a beneficiary, submit supporting documents, approve a payment, track its status, and reconcile the completed transaction without unnecessary back-and-forth? Evaluate support during this stage as carefully as the product itself. International payments can become time-sensitive quickly.
Finally, choose a setup that matches your operating maturity. A small importer may value transparent FX and dependable supplier payouts over a complex API. A multi-country platform may need integration depth and mass-payment controls. The most effective choice is the one that gives your business a clear path from funds received to funds settled, with pricing, compliance, and accountability visible at every step.
When a payment crosses borders, certainty has commercial value. Build your payment stack around the corridors you use most, the controls your team can maintain, and a provider prepared to support the transaction after the payment instruction is submitted.