Treasury & Operations
KYC Versus KYB Checks: What Businesses Need
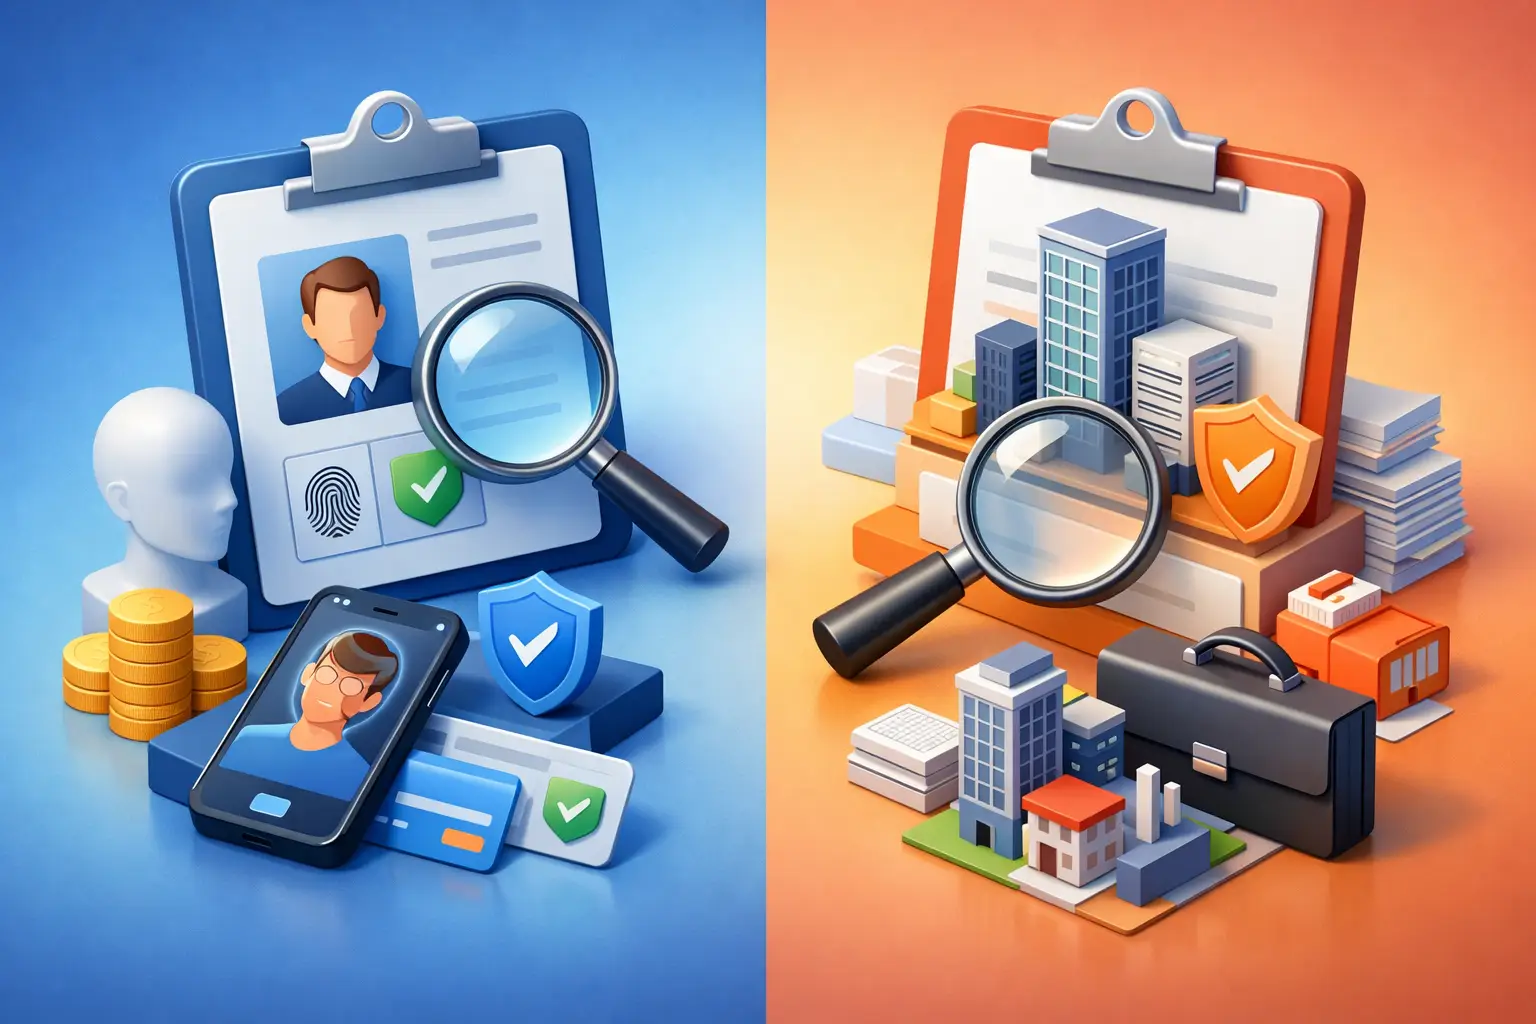
A delayed verification can hold up a supplier payment, a currency conversion, or a time-sensitive international settlement. That is why understanding KYC versus KYB checks matters for anyone moving money across borders. They are related compliance processes, but they answer different questions: KYC establishes who an individual is, while KYB establishes whether a business is legitimate and who ultimately controls it.
For African businesses and professionals trading internationally, this distinction is more than a regulatory formality. It affects how quickly accounts can be activated, how safely payments can be processed, and how confidently counterparties can transact across Europe, Asia, North America, Australia, and South America.
What Is KYC?
Know Your Customer, or KYC, is the process financial institutions use to verify an individual's identity. It helps payment providers, foreign exchange platforms, banks, and other regulated businesses confirm that a customer is real, understand the intended relationship, and identify potential risk before funds move.
A standard KYC process usually begins with basic personal information, such as a full legal name, date of birth, residential address, phone number, and email address. The customer is then asked to provide a government-issued identity document, which may be a passport, driver's license, or national identity card. Depending on the service, verification can also include a selfie, liveness check, proof of address, or validation against trusted data sources.
The purpose is not simply to collect documents. Effective KYC connects those documents to a real person and assesses whether that person can safely use the financial service. It also supports screening for sanctions exposure, politically exposed person status, fraud indicators, and adverse media where required by the risk profile.
For an individual sending funds to family, paying overseas tuition, converting currency for travel, or receiving international business income, KYC creates the trust foundation for the transaction. It helps reduce impersonation, account takeover, and the misuse of payment channels for financial crime.
What Is KYB?
Know Your Business, or KYB, extends due diligence to companies, partnerships, sole proprietorships, and other legal entities. A business account cannot be evaluated solely by verifying the person opening it. The financial provider must also determine whether the organization exists legally, what it does, where it operates, and who owns or controls it.
KYB checks commonly review business registration details, incorporation records, tax or operating information where relevant, registered addresses, and the nature of the company's activity. They also identify directors, authorized signatories, and ultimate beneficial owners, often called UBOs. A UBO is generally a person who ultimately owns or exercises significant control over the business, even if their name does not appear on day-to-day company documents.
This matters because a legitimate-looking company can be used to hide illicit activity if its ownership and purpose are not properly understood. Business verification helps financial institutions assess whether transactions are consistent with the company's stated operations. For example, the expected payment activity of a logistics company will differ from that of a digital agency, commodity importer, or professional services firm.
KYB may take longer than individual verification because corporate structures vary widely. A simple sole proprietorship with one owner is different from a company with several directors, foreign shareholders, and holding entities across multiple jurisdictions. The right process should be thorough without forcing every low-risk business through the same level of review.
KYC Versus KYB Checks: The Core Difference
The simplest distinction is that KYC verifies people, while KYB verifies businesses and the people behind them.
KYC asks questions such as: Is this customer who they claim to be? Is their identity document valid? Does their profile present a risk that needs further review?
KYB asks a broader set of questions: Is this company properly established? What services or goods does it provide? Who owns it, directs it, and has authority to move money? Does its expected payment activity make commercial sense?
A business verification process nearly always includes elements of KYC. Directors, account signatories, and beneficial owners typically need individual identity verification. In that sense, KYB is not a replacement for KYC. It is a deeper framework that combines entity validation, ownership analysis, and individual due diligence.
The table below illustrates the practical difference.
| Area | KYC | KYB | |---|---|---| | Primary subject | An individual customer | A company or legal entity | | Main purpose | Confirm identity and assess personal risk | Confirm business legitimacy, ownership, and operational risk | | Typical evidence | ID document, selfie, proof of address | Registration records, ownership details, director information, business activity | | People reviewed | The customer | Directors, signatories, and beneficial owners | | Common use case | Personal FX, remittances, individual accounts | Business payments, merchant accounts, corporate FX, and B2B settlements |
Why Both Checks Matter for Cross-Border Payments
International transactions involve more variables than local payments. Funds may pass through different financial institutions, currencies, and legal jurisdictions before reaching the recipient. A payment that appears routine at one point can create compliance concerns if the sender, recipient, business purpose, or ownership structure is unclear.
KYC and KYB give payment providers a clearer view of who is participating in the transaction. This helps prevent fraud, money laundering, terrorist financing, sanctions breaches, and the use of shell entities to disguise the true source or destination of funds.
For legitimate customers, good compliance can also reduce unnecessary disruption. When customer information is accurate and current, providers can handle reviews more efficiently and request fewer follow-up documents. That is particularly valuable for importers paying overseas suppliers, exporters receiving foreign currency, and finance teams managing recurring settlements.
There is a business credibility benefit, too. Overseas suppliers, partners, and financial providers are more likely to work confidently with organizations that can demonstrate clear ownership, proper documentation, and a traceable payment history. Compliance supports access to the global financial system - it does not sit outside commercial growth.
What Makes Verification Slow or Difficult?
Most delays are not caused by the existence of KYC or KYB itself. They happen when information is incomplete, inconsistent, expired, or difficult to verify.
For individuals, common issues include submitting an unclear ID image, using an expired document, entering a name that does not match the identification record, or providing an address document that is too old. For businesses, delays often arise when incorporation documents do not show current ownership, directors are missing from filings, beneficial ownership is unclear, or the business activity is described too broadly.
Cross-border businesses can face additional complexity when registration, operations, and ownership are spread across countries. A company may be incorporated in one jurisdiction, source goods from another, and receive payments in a third. That structure is not automatically a problem, but it requires a clear commercial explanation and supporting records.
The practical answer is preparation. Keep identification current, use the same legal name across records where possible, maintain up-to-date company filings, and be ready to explain the purpose and expected pattern of international payments. A well-organized compliance file makes reviews faster when transaction volumes increase or new corridors are added.
A Risk-Based Approach Is Better Than a One-Size-Fits-All Process
Not every customer or business carries the same level of risk. A low-value personal transfer from a verified customer may require less ongoing review than a high-value corporate payment involving multiple beneficial owners and a new overseas counterparty.
This is why responsible financial providers use a risk-based approach. They apply appropriate verification at onboarding, then monitor relationships and transactions over time. Higher-risk situations may require enhanced due diligence, additional evidence of funds or business activity, or more frequent information updates.
The trade-off is clear: a process that is too light creates exposure to fraud and regulatory action, while a process that is unnecessarily burdensome frustrates legitimate customers and delays commerce. The goal is not paperwork for its own sake. The goal is reliable verification that protects customers while keeping legitimate payments moving.
For businesses, automation can make a meaningful difference. API-based compliance tools can validate identity data, check company records, screen relevant risk lists, and flag inconsistencies earlier in the onboarding process. Human review remains essential for complex or higher-risk cases, but technology can reduce manual errors and create a more consistent customer experience.
How to Prepare for KYC and KYB Reviews
Individuals should use a valid government-issued ID, ensure personal details match their documents, and provide clear images in good lighting. If proof of address is requested, use a recent document that shows the same name and residential address used for the account.
Businesses should maintain a current set of incorporation records, ownership details, director information, and evidence of their operating activity. Depending on the payment purpose, invoices, contracts, shipping records, or supplier agreements may also help explain transactions. Finance teams should establish an internal process for updating these documents when directors, shareholders, addresses, or expected payment activity changes.
The strongest compliance experience is proactive. Waiting until an urgent supplier payment is under review creates avoidable pressure. Completing verification early and keeping records current gives your business more control over timing.
ParkPay supports customers with technology-led compliance processes designed for secure identity verification and customer due diligence alongside FX and cross-border payment needs. For individuals and businesses alike, the standard is simple: provide accurate information, understand what is being requested, and work with a provider that treats compliance as a safeguard for your money and your reputation.
When international payments are central to your personal or business plans, clear KYC and KYB records are not a hurdle to work around. They are part of the infrastructure that helps your funds move with greater confidence.