Treasury & Operations
Digital Onboarding Compliance Guide for Payments
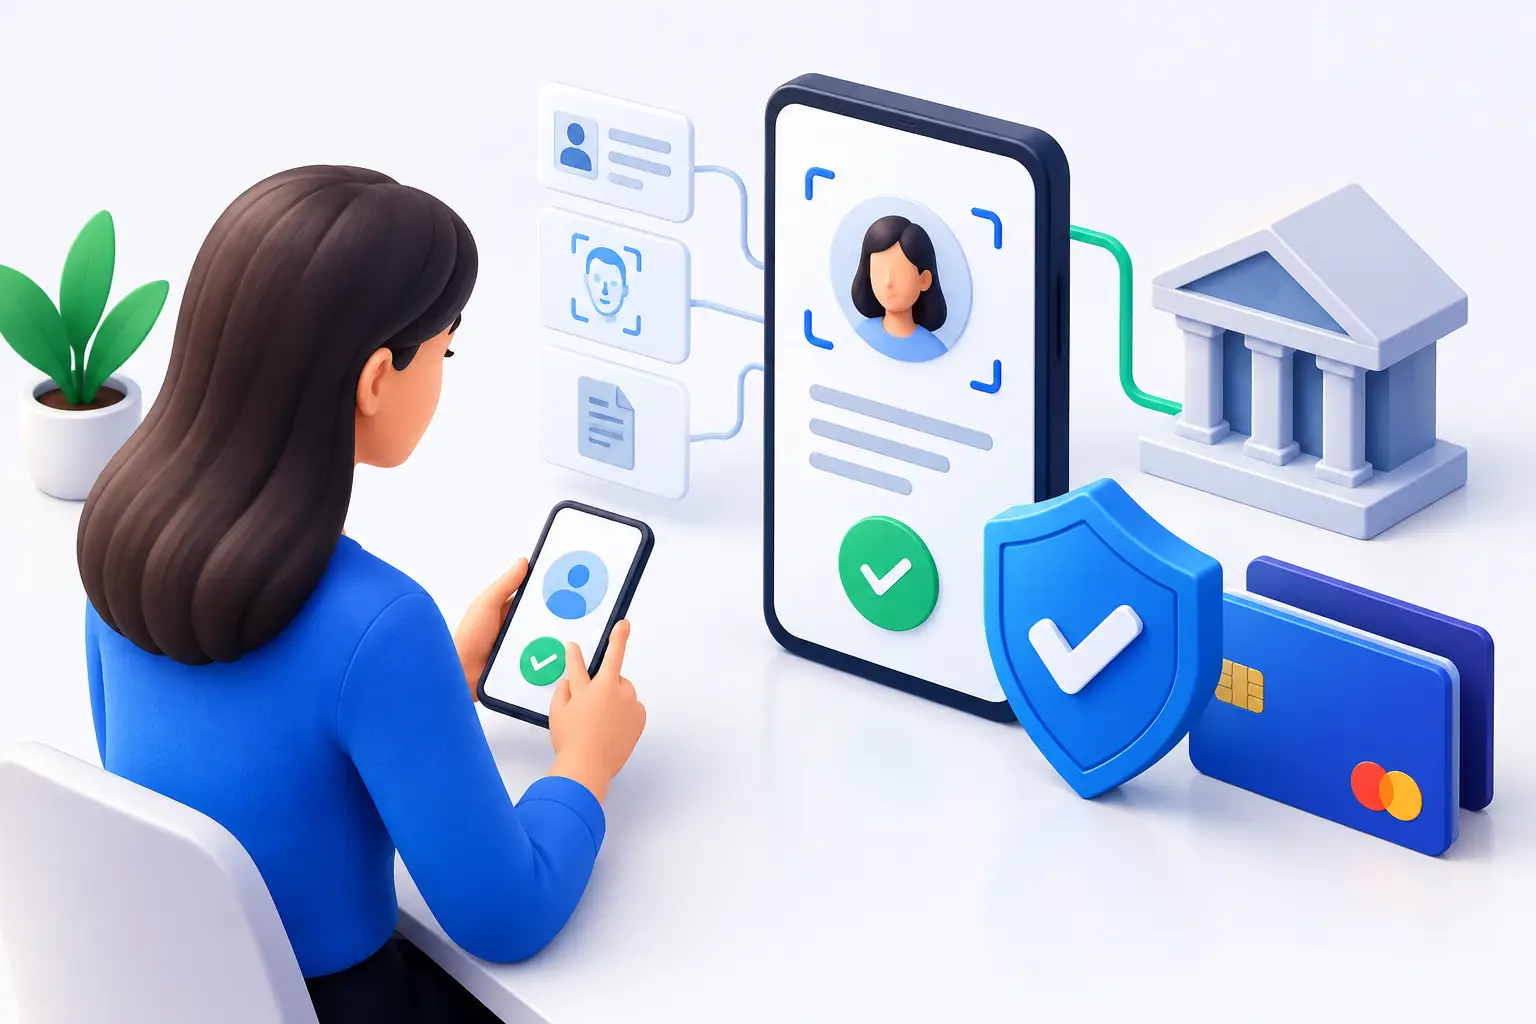
A customer can decide whether to trust a payment provider before their first transfer is complete. If account setup asks for unnecessary documents, gives unclear instructions, or delays a legitimate payment without explanation, confidence drops quickly. A well-designed digital onboarding compliance guide helps financial businesses verify customers properly while keeping legitimate individuals and businesses moving.
For Africa-to-global payment corridors, this balance is especially important. A freelancer receiving international income, an importer paying an overseas supplier, or a finance team managing multi-country settlements may all need fast access to FX and payment services. Yet each transaction carries compliance responsibilities. Good onboarding is not simply a form to complete. It is the first control point for protecting customers, meeting regulatory obligations, and supporting safe growth.
Why Digital Onboarding Matters in Cross-Border Payments
Digital onboarding brings identity verification, customer due diligence, risk assessment, and account approval into a structured online process. Done well, it reduces repetitive manual work and gives compliance teams a clearer record of why an account was approved, restricted, or referred for review.
Speed matters, but speed alone is not the goal. Approving every customer instantly can expose a business to fraud, impersonation, sanctions concerns, and financial crime risk. Requiring every customer to complete the same intensive review creates the opposite problem: unnecessary friction for low-risk users and overloaded operations teams. The right approach is risk-based.
For example, an individual making occasional transfers may need a different level of review than a company sending high-value payments to multiple suppliers across several countries. Their onboarding journeys should not be identical. The information collected, checks performed, and monitoring applied should reflect the service requested, expected activity, customer type, and relevant jurisdictions.
Digital Onboarding Compliance Guide: The Core Controls
A reliable process begins by defining what the organization needs to know before it provides FX, payment, or settlement services. That definition should come from applicable regulations, licensing requirements, internal risk appetite, and the specific markets served. Compliance policies should be reviewed by qualified legal and regulatory professionals where required.
Verify identity and customer information
Identity verification should establish that the customer is real and that the details provided are credible. For individuals, this commonly includes legal name, date of birth, address, government-issued identification, and a method to confirm that the person opening the account is the document holder.
Digital document capture, facial comparison, liveness checks, address verification, and device signals can support this process. No single data point is perfect. A clear image of an ID does not, by itself, confirm that the person presenting it is legitimate. Combining verification methods produces a more reliable decision and creates an auditable record.
For business customers, the review should go further. Verify the legal entity, registration status, business address, directors, and authorized account users. Identify beneficial owners and understand who ultimately owns or controls the organization. This is essential where company structures, intermediaries, or overseas counterparties make ownership less obvious.
Screen for sanctions, PEPs, and adverse information
Customer due diligence should include screening against relevant sanctions lists, politically exposed person records, and credible adverse media sources. Screening must cover more than the applicant's exact name. Name variations, date of birth, nationality, location, and ownership relationships may all be needed to distinguish a true match from a false positive.
A screening alert is not an automatic reason to reject a customer. It is a prompt for investigation. Teams need documented procedures for reviewing alerts, recording evidence, escalating higher-risk cases, and applying restrictions when necessary. Treating every alert as a rejection damages the customer experience. Ignoring alerts creates a far greater risk.
The same principle applies to beneficial owners, company directors, and authorized signatories. A B2B payment account can introduce risk through the people behind the entity, not only through the business name on its registration certificate.
Build a practical customer risk profile
Risk profiling turns onboarding data into a proportionate decision. Consider the customer's location, occupation or industry, expected payment volumes, source of funds, destination countries, counterparties, payment purpose, and anticipated FX activity. For business accounts, the nature of goods or services sold can also be relevant.
A low-risk customer may be approved after standard checks. A higher-risk customer may require enhanced due diligence, additional source-of-funds evidence, senior compliance approval, or lower initial transaction limits. The purpose is not to exclude legitimate customers because they operate internationally. It is to understand whether their expected activity makes sense and whether the business can manage the associated risk.
Risk is not static. An account that was low risk at signup can change as transaction patterns, ownership, or geographic exposure change. Onboarding should establish a starting profile that supports ongoing monitoring rather than a one-time compliance event.
Design the Journey Around Clear Decisions
A compliant journey can still be simple. Ask only for information that serves a defined verification or risk purpose. Explain why documents are requested and show customers what an acceptable submission looks like. A vague request for “more information” causes delays. A specific request for a readable passport image, proof of address dated within the required period, or an invoice supporting a business payment gives the customer a practical next step.
Automation is most effective when it handles routine, low-risk decisions and routes exceptions to trained reviewers. A rules engine can flag expired documents, failed liveness checks, inconsistent names, high-risk geographies, or transaction expectations that do not align with the account profile. Human judgment remains necessary for complex ownership structures, ambiguous screening results, and unusual but legitimate commercial activity.
Four operating practices make the process more dependable:
- Collect consent and provide clear privacy notices before using identity and verification data.
- Maintain an audit trail showing submitted information, verification results, reviewer actions, and approval rationale.
- Set service-level targets for manual review so valid customers are not left waiting without updates.
- Apply re-verification triggers when documents expire, ownership changes, risk increases, or activity materially shifts.
For a payment business, onboarding data should connect to transaction monitoring. If a customer states they expect to send modest supplier payments to two countries, sudden high-value transfers to unrelated destinations deserve review. The system should not assume wrongdoing, but it should recognize that the account behavior no longer matches the known profile.
Measure Compliance and Customer Experience Together
A digital onboarding process should be measured with both control and service outcomes in mind. Approval rate alone is misleading. A very high approval rate may indicate weak controls, while a low rate can suggest poor document guidance, biased rules, or an overly restrictive risk model.
Track completion rates, time to verification, manual review volumes, false-positive screening alerts, document failure reasons, and customer support contacts during onboarding. Segment the data by customer type, corridor, document type, and risk level. This reveals where customers are abandoning the process and where operational effort is being consumed.
For instance, repeated address-verification failures may point to a document requirement that does not fit a particular market. A rise in manual reviews for a certain business category may signal that the risk rules need refinement or that reviewers need clearer decision guidance. Strong compliance operations learn from these patterns without lowering standards.
When Manual Review Is the Right Choice
Not every exception should be forced through automation. Manual review is often appropriate when a customer's legal name varies across legitimate documents, a business has multiple shareholders in different countries, or source-of-funds evidence needs commercial context. It is also appropriate when a customer is linked to a potential sanctions or PEP match that requires careful investigation.
The key is consistency. Reviewers need defined escalation paths, case notes, quality assurance checks, and authority limits. Customers also need timely communication. A request for more information should explain what is needed without disclosing sensitive internal controls or creating unnecessary confusion.
ParkPay's approach to cross-border payments and compliance should reflect the same standard: secure verification, transparent processes, and operational support that helps legitimate customers transact with confidence.
The best onboarding experience does not make compliance disappear. It makes compliance understandable, proportionate, and dependable from the first verification step to every payment that follows.