Treasury & Operations
Business Payment API for Cross-Border Control
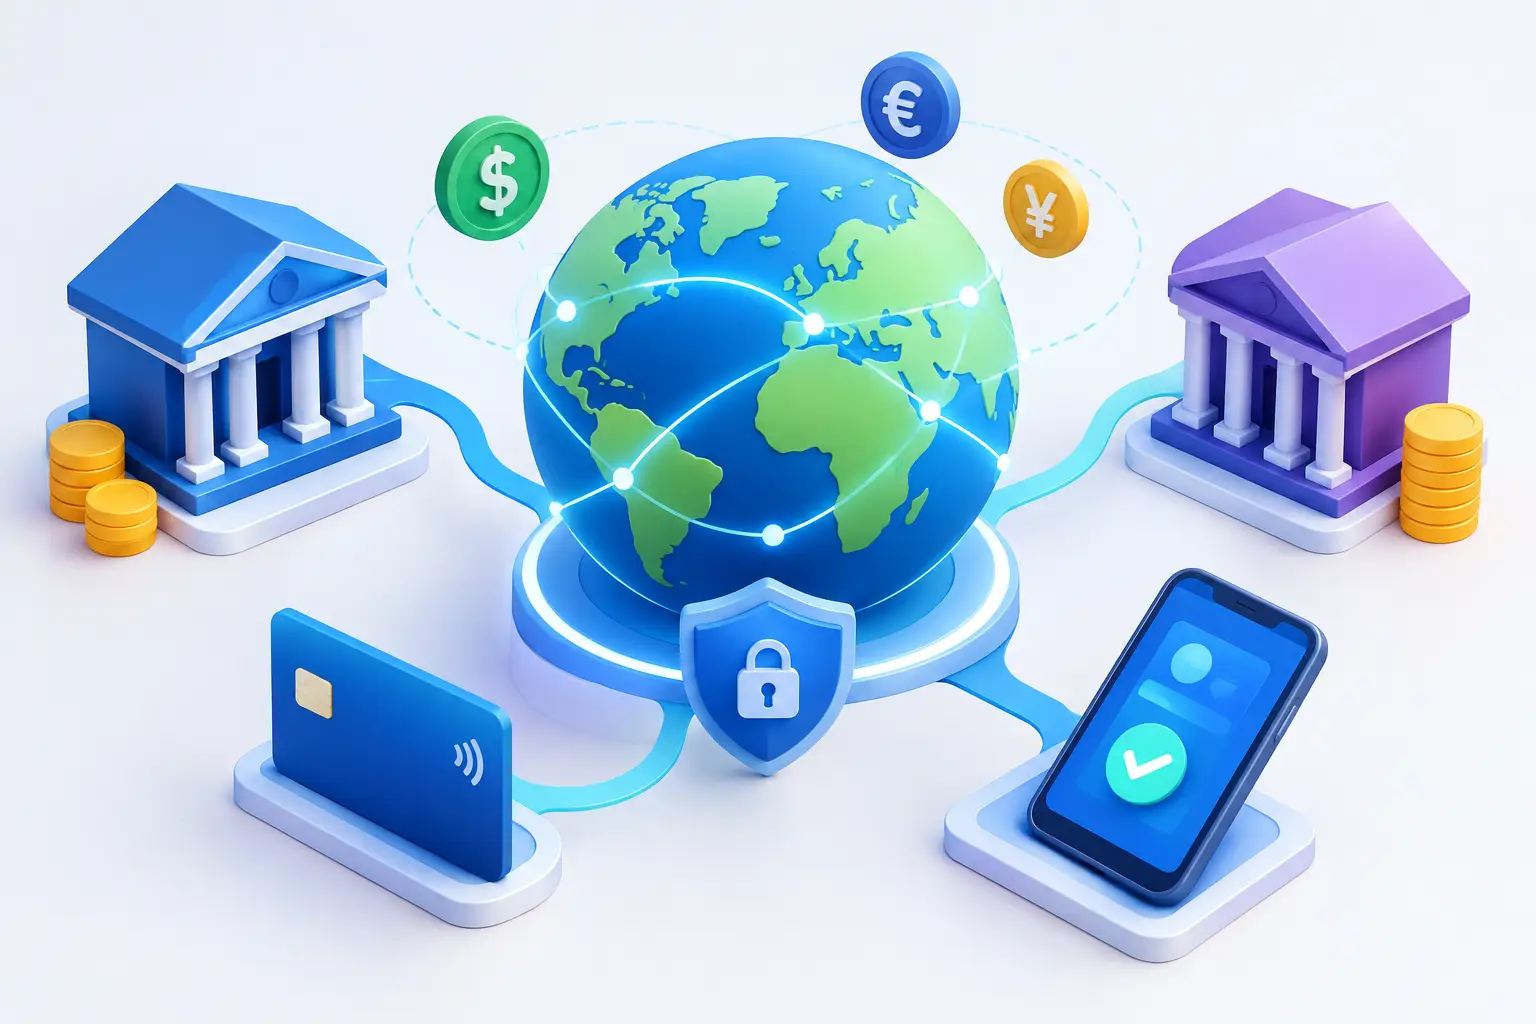
A supplier cannot wait three days for a payment team to confirm whether funds have arrived. A business payment API gives finance teams a structured way to initiate, monitor, reconcile, and control payments from the systems they already use. For businesses trading between Africa and global markets, that control can reduce manual work, limit payment errors, and provide clearer visibility into currency conversion and settlement status.
The value is not simply sending money through a piece of software. It is creating a dependable payment operating model for vendor settlements, marketplace payouts, payroll, treasury movements, and customer refunds. The right implementation connects payment execution with the business rules, approval flows, and compliance checks that protect every transaction.
What a business payment API does
A business payment API is a set of secure technical connections that allows a company’s application, enterprise resource planning platform, accounting tool, or internal finance portal to communicate directly with a payment provider. Instead of logging in to a dashboard and processing each transfer manually, authorized systems can submit payment instructions programmatically.
A typical payment request can include the payer entity, beneficiary details, payment amount, currency, purpose of payment, supporting reference, and preferred settlement route. The API then returns a response that confirms whether the request has been accepted, requires review, or cannot proceed. As the payment moves through its lifecycle, status updates can be delivered to the business system.
That lifecycle matters. A payment marked as submitted is not necessarily settled. Finance teams need to distinguish between initiated, approved, funded, processing, completed, returned, and failed transactions. Clear status data prevents the common and expensive problem of treating an instruction as a completed payment before the beneficiary can access the funds.
For cross-border activity, the API can also support foreign exchange workflows. A business may request a quote, confirm the exchange rate, convert funds, and send the resulting currency to a beneficiary through a connected process. This is particularly useful when an importer in Africa pays an overseas supplier, or when a global company needs to settle local vendors in multiple markets.
Why payment infrastructure matters for cross-border teams
Manual payments often seem manageable until transaction volume, currencies, and approval requirements increase. A finance professional may need to collect beneficiary information from email, verify bank details, request a rate, prepare a payment file, obtain approval, enter the transfer, and update the accounting system. Every handoff creates delay and increases the chance of error.
A well-designed API replaces repeated rekeying with controlled data flows. For example, an accounts payable system can send approved invoices for payment only after the required approver has signed off. Once the payment is completed, the payment reference and settlement status can return to the original system. The team has a clearer audit trail without building spreadsheets to bridge disconnected tools.
This is also where operational speed becomes commercially significant. An exporter waiting for proceeds may need to purchase inventory. A distributor may need to pay a manufacturer before goods are released. A contractor may need prompt payment to continue a project. Faster, more visible settlements help businesses make commitments with greater confidence.
However, speed should not mean bypassing controls. Cross-border payments can involve different banking requirements, sanctions considerations, currency restrictions, and beneficiary validation rules. The best infrastructure makes these requirements easier to manage within the workflow rather than treating compliance as a separate task after a payment has been created.
Core capabilities to look for in a business payment API
Not every API is built for the same payment environment. Some are designed mainly for card payments, while others support account-to-account transfers, local disbursements, foreign exchange, or high-value business settlements. Before selecting a provider, finance and technology leaders should assess the payment routes they actually need.
Payment initiation and beneficiary management
The API should allow a business to create and manage beneficiaries securely, validate required payment fields, and submit payment instructions with unique references. Idempotency support is especially valuable. It helps prevent duplicate payments if a system retries a request after a timeout or connection issue.
Beneficiary data should not be treated as a simple form field. Incorrect account details can result in failed transfers, recovery work, and damaged commercial relationships. Look for clear validation requirements and processes for managing changes to beneficiary information.
FX quotes and rate visibility
For multi-currency payments, businesses need to know when a rate is available, how long it is valid, and what amount the beneficiary will receive. A quote-based workflow can give the finance team a defined rate before it commits to the transaction.
The right approach depends on the business. A company making occasional supplier payments may prioritize transparent quoted rates at the point of transfer. A business with recurring, higher-value currency exposure may need tighter treasury processes, rate monitoring, and approval thresholds. In either case, hidden FX costs and unclear conversion timing make reconciliation harder.
Real-time status updates and webhooks
An API response tells your system that a request was received. Webhooks or event notifications tell it what happens next. These updates can trigger internal actions automatically, such as marking an invoice as paid, notifying a vendor, escalating an exception, or updating a cash forecast.
Teams should design for exceptions rather than assuming every payment will complete immediately. Beneficiary banks may reject a transfer, additional documentation may be required, or a payment may be placed under review. A useful integration captures the reason code, routes the issue to the right team, and keeps the original payment record intact.
Security, permissions, and auditability
Payment access needs strong authentication, encrypted data transmission, role-based permissions, and detailed logs. A junior operations user should not have the same authority as a finance director approving large international settlements. The API and the business’s internal tools should reflect that distinction.
Auditability is equally practical. When a vendor asks about a payment, the team should be able to identify who initiated it, which invoice it relates to, which rate was applied, the current status, and the final settlement reference. That record supports both customer service and financial control.
How to implement a business payment API without creating new risk
The most effective projects start with a clear payment map, not a rushed technical build. Identify the payment types the business handles, the currencies involved, expected volumes, approval rules, cut-off times, and exception scenarios. This reveals whether one workflow can cover everything or whether supplier payments, refunds, and treasury transfers need different controls.
Next, define the source of truth for each data point. Your enterprise resource planning system may own invoices and approval status. The payment provider may own execution status and settlement references. Your accounting system may own the final ledger entries. When ownership is unclear, reconciliation issues tend to follow.
Test in stages. Start with a limited payment use case and a small group of approved beneficiaries. Test successful transactions as well as rejected account details, duplicate requests, expired FX quotes, insufficient balances, and delayed status updates. The purpose is not just to prove that a payment can be sent. It is to confirm that the business knows what to do when a payment does not proceed as planned.
Finally, set operational ownership. Technology teams can maintain the integration, but finance teams need procedures for approving payments, investigating exceptions, reconciling balances, and responding to suppliers. A payment API is most valuable when its technical design and daily operating process work together.
Choosing a provider for Africa-to-global payments
Coverage is important, but it is not the only decision factor. A provider may support a destination country while offering limited settlement options, unclear pricing, or weak support for the payment purpose and documentation your business requires. Ask how the provider handles the specific corridors your company uses, including local currency collection, foreign currency conversion, beneficiary payout methods, and payment tracking.
You should also evaluate transparency. Understand the exchange rate process, payment fees, expected settlement windows, transaction limits, required compliance information, and support path when an urgent payment needs attention. For regulated cross-border activity, confidence comes from knowing how funds move and who is accountable at each step.
ParkPay is designed for businesses that need FX execution, local and international settlements, and compliance support in a more connected operating flow. For teams moving funds between African markets and Europe, Asia, North America, Australia, or South America, that combination can reduce the friction of managing separate providers for conversion, payment, and verification.
A business payment API should make every transaction easier to control, not merely easier to initiate. Start with the payment flow that creates the most manual effort or uncertainty today, build the right checks around it, and let reliable transaction data improve the next decision your finance team makes.